Money Apps in 2026: The Beginner’s Guide to Smarter Spending
Money apps have quietly become the control panel for everyday finances in 2026. They track spending, automate savings, split bills, and even nudge you before an overdraft hits. If you have felt overwhelmed by paper statements or scattered spreadsheets, the right app turns chaos into a clear, calm dashboard.
This guide explains how these tools work, which categories matter, and how to pick one that fits your life. You do not need to be a numbers person. You just need a phone, a few minutes, and a willingness to let automation do the heavy lifting.
Why Money Apps Matter More Than Ever
Bank branches keep shrinking, and daily life keeps moving faster. In response, people now expect to manage cash from the same screen they use for messaging. A recent Pew Research Center analysis shows mobile banking has become the primary way many adults check balances and move money.
That shift rewards anyone who embraces it. Good money apps surface hidden subscriptions, flag duplicate charges, and show your true spending pace mid-month. Instead of reacting to a scary statement, you adjust in real time. That single habit change often saves more than any coupon ever could.
The Core Jobs a Money App Should Do
Before you download anything, decide what problem you want solved. Most people need one or two of these jobs handled well, not fifteen features they will never open.
- See spending: Categorize transactions automatically across every account.
- Save automatically: Move small amounts to savings without you noticing.
- Send and receive: Pay friends, family, or freelancers instantly.
- Grow money: Round up purchases or invest spare change.
- Guard your credit: Alert you to score changes and suspicious activity.
The Main Categories of Money Apps
Not every app tries to do everything, and that is a feature, not a flaw. Understanding the categories helps you avoid clutter and choose with intent.
Budgeting and Tracking Apps
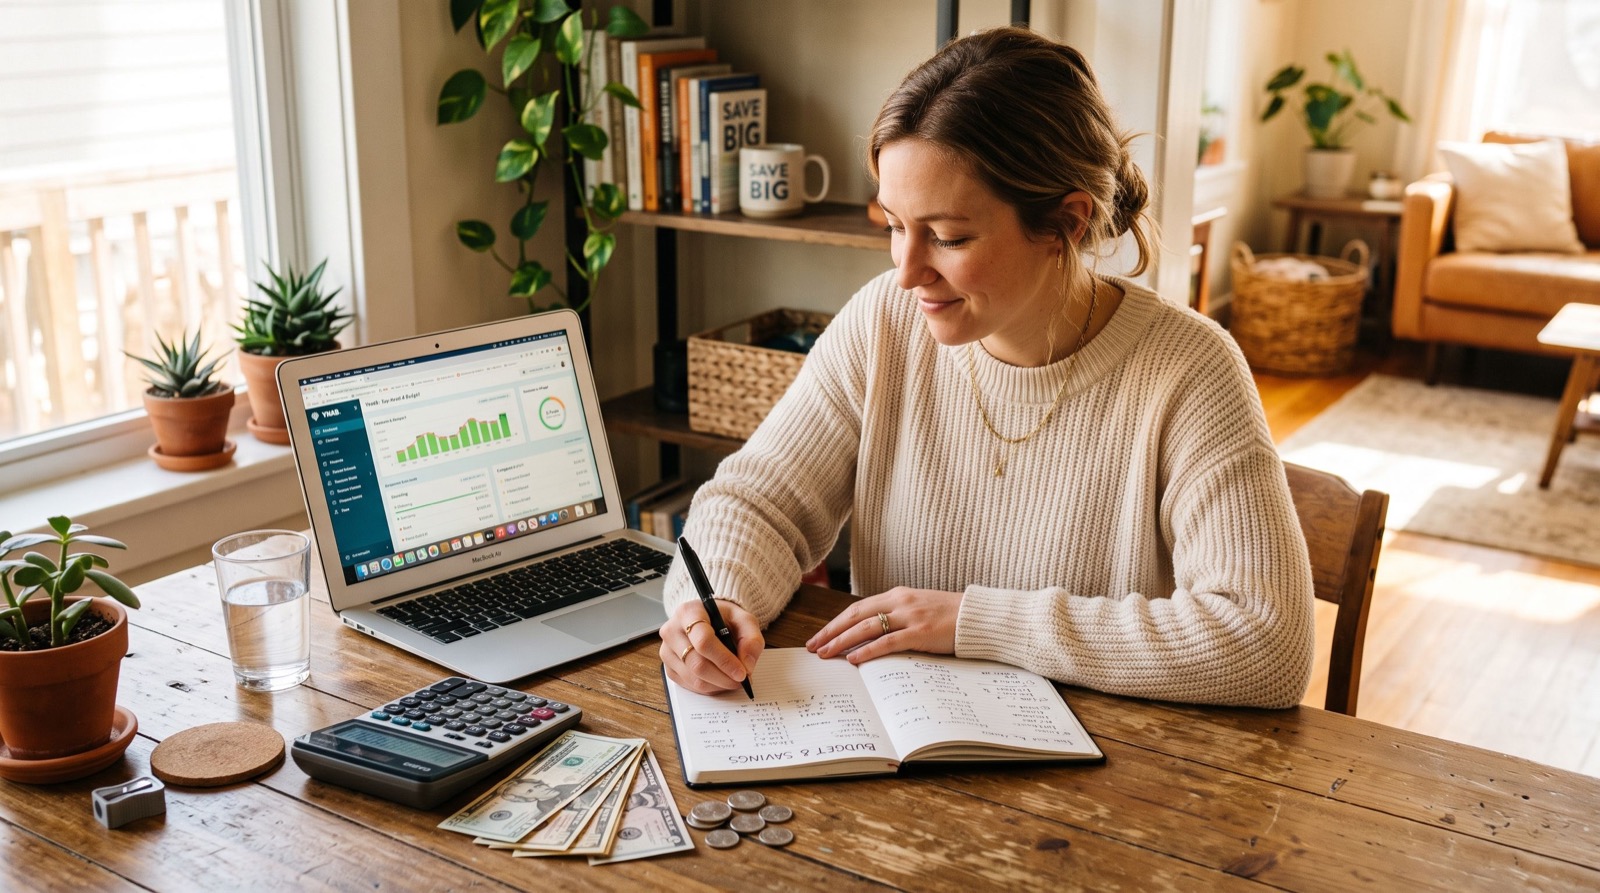
These connect to your accounts and paint a picture of where cash actually goes. They shine at exposing the slow leaks: streaming services you forgot, delivery fees that add up, and impulse buys that felt small. Seeing the pattern is often enough to change it.
Peer-to-Peer Payment Apps
Splitting rent or repaying a friend used to mean cash or awkward reminders. Payment apps settle it in seconds. Many now include a debit card, direct deposit, and basic saving tools, so they double as a lightweight bank.
Automated Savings and Investing Apps
The best savers rarely rely on willpower. They rely on automation. These apps sweep a few dollars into savings on payday or round up each purchase to the nearest dollar and invest the difference. Small, invisible transfers grow into a real cushion over a year.
How Do the Main Money App Types Compare?
Choosing gets easier when you see the trade-offs side by side. The table below sums up the four most common categories and who each one suits best.
| App Type | Best For | Typical Cost | Watch Out For |
|---|---|---|---|
| Budgeting tracker | Seeing spending clearly | Free or low monthly fee | Sync errors across banks |
| Peer-to-peer payments | Splitting and sending cash | Free; fees for instant transfer | Scams from strangers |
| Auto-savings | Building a cushion hands-free | Free or small fee | Overdraft if timing is off |
| Micro-investing | Starting to invest small sums | Flat monthly fee | Fees eating tiny balances |
How to Choose the Right App for You
The perfect app is the one you actually open. Flashy features mean nothing if the interface frustrates you. Use this simple, ordered process to pick with confidence.
- Name your top goal: track, save, send, or invest.
- Check that it supports your bank and card.
- Read the fee page slowly, including instant-transfer charges.
- Confirm it uses encryption and two-factor login.
- Test the free tier for two weeks before paying.
One original tip from real use: set up the app on payday, not on a random Tuesday. When your first automated transfer lands the same day your salary arrives, the habit sticks immediately. Trying to start mid-cycle almost always fizzles.
Security Habits That Protect Your Money
Convenience should never cost you safety. Enable biometric login, turn on transaction alerts, and never send money to someone you have not verified. If an app offers a separate savings vault with a slight withdrawal delay, use it. That tiny friction stops impulse spending.
When you want a deeper walkthrough or a vetted shortlist, lean on reviewers who test these tools daily. A curated roundup of the best money apps saves hours of trial and error and steers you away from products with hidden fees.
Making the Most of Automation in 2026
The real power of money apps is not tracking; it is automation working while you sleep. Set rules once and the app enforces them forever. Automate a payday transfer, a round-up on every card swipe, and a bill reminder three days before each due date.
Layer these small rules and they compound. A person who rounds up every purchase and sweeps ten dollars each week barely notices the outflow, yet ends the year with hundreds saved. Automation beats motivation because it never has a bad day or a busy week.
Review your rules once a quarter. Life changes, income shifts, and goals evolve. A ten-minute check keeps your automation aligned with reality instead of quietly working against you.
Common Mistakes New Users Make
Most frustration comes from a handful of avoidable errors. Sidestep these and your experience improves fast.
- Linking every account at once and drowning in data.
- Ignoring notification settings, then missing key alerts.
- Paying for premium tiers before using the free features.
- Forgetting to review categories, which skews the reports.
Start small. Link one checking account, watch it for a week, and expand only when the routine feels natural. Momentum beats perfection every time.
Frequently Asked Questions
Are money apps safe to use in 2026?
Reputable apps use bank-level encryption, two-factor authentication, and read-only account connections. Stick to well-reviewed apps, enable biometric login, and you significantly lower your risk compared with carrying cash or emailing account details.
Do money apps cost anything?
Many offer a solid free tier. You typically pay only for premium budgeting features, instant transfers, or micro-investing subscriptions. Always read the fee page before you rely on any paid function.
Can one app handle budgeting, saving, and payments?
Some all-in-one apps combine these jobs, but they rarely excel at all three. Many people pair a strong budgeting tracker with a separate payment app for the best of both worlds.
How do I switch apps without losing my data?
Export your transaction history first, note your recurring categories, then link accounts to the new app gradually. Run both for a month so nothing slips through during the transition.
Final Thoughts
Money apps reward small, steady habits far more than dramatic budget overhauls. Pick one clear goal, choose a trusted tool, and let automation carry the effort. If you prefer guidance from an experienced local team when comparing digital services, use it to shortcut the learning curve. Start today, and by the end of 2026 you will spend with clarity and save without stress.